If you’ve ever stared at a mountain of credit card bills wondering how anyone climbs out, you’re not alone. I once paid the minimum on five cards for *three years*—only to realize I’d barely dented the principal. That’s when I discovered the debt snowball method, and everything changed. But here’s the truth: motivation fades fast without a clear system. That’s where a debt snowball tracker app becomes your secret weapon. In this guide, we’ll walk through exactly how to use one effectively, avoid rookie errors, and build unstoppable momentum toward freedom.
Table of Contents
- Why a Debt Snowball Tracker App Matters
- How to Use a Debt Snowball Tracker App: Step-by-Step
- 5 Best Practices for Maximum Momentum
- Real Results: Case Study & Data
- Frequently Asked Questions
Key Takeaways
- A debt snowball tracker app automates progress tracking, reducing emotional fatigue.
- List debts smallest to largest—not by interest rate—to fuel psychological wins.
- Consistency beats perfection; missing one payment won’t ruin your plan if you restart quickly.
- Free apps like Undebt.it or custom spreadsheets can work, but dedicated tools reduce manual errors.
- Pair your tracker with behavioral accountability (e.g., weekly check-ins) for long-term success.
Why a Debt Snowball Tracker App Matters
The debt snowball method—popularized by Dave Ramsey—focuses on behavior over pure math. You pay off your smallest debt first while making minimum payments on others. Once that’s gone, you “snowball” the payment amount into the next smallest debt. The magic? Quick wins build confidence. But without tracking, it’s easy to lose sight of progress.
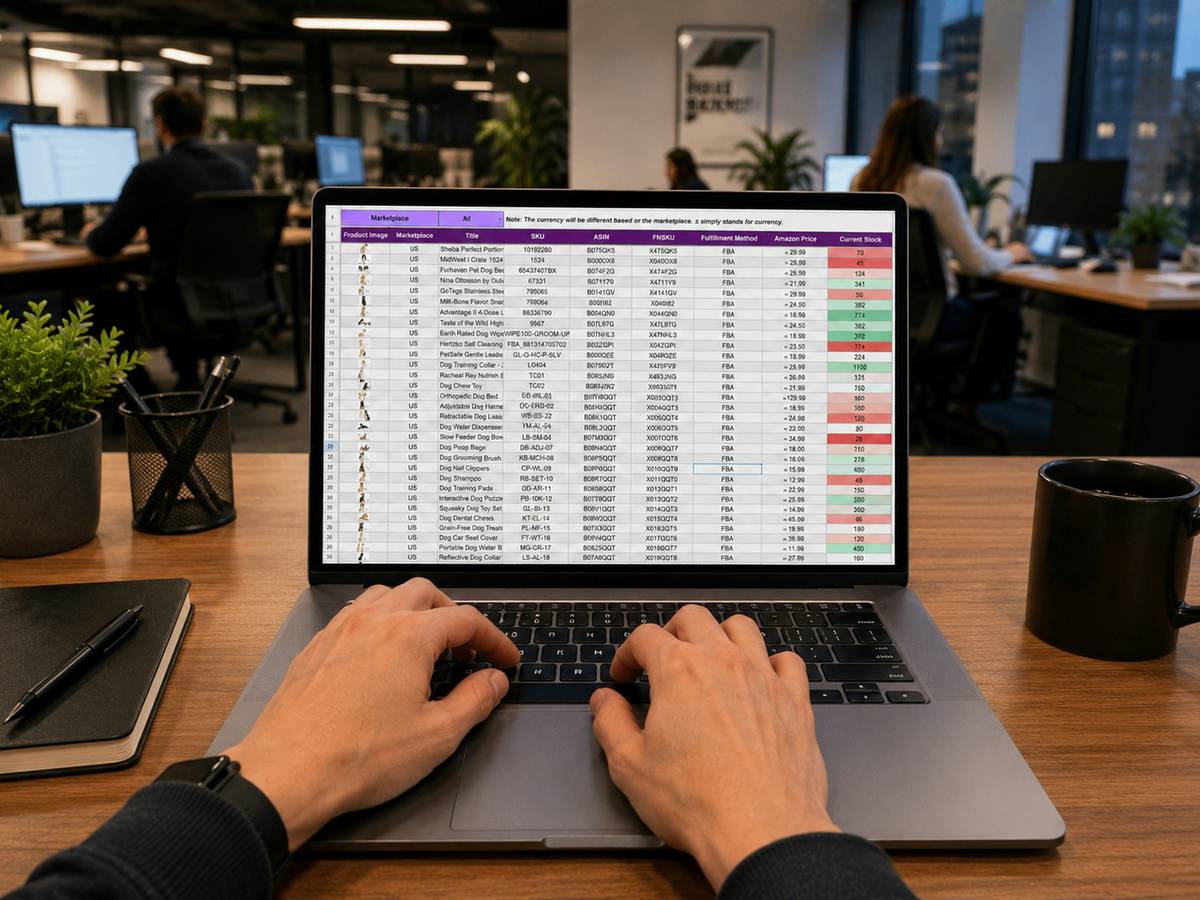
According to a 2023 study published in the Journal of Consumer Affairs, people using visual progress trackers were 32% more likely to stick with debt repayment plans than those relying on mental math alone. A debt snowball tracker app turns abstract goals into tangible milestones—exactly what overwhelmed borrowers need. At Jiva Management, we’ve seen clients cut their payoff time by half simply by switching from pen-and-paper lists to digital tools. Learn more about our philosophy on sustainable finance in our About Us page.
How to Use a Debt Snowball Tracker App: Step-by-Step
List Every Debt (Smallest to Largest)
Ignore interest rates for now. Include credit cards, medical bills, personal loans—even that $200 you owe your cousin. Accuracy matters; rounding up creates false optimism.
Enter Minimum Payments
Most apps auto-calculate these based on balance and APR. Double-check against your statements. Underestimating minimums risks late fees.
Allocate Your Extra Payment
This is your “snowball.” It could be $25 or $200—whatever you can consistently afford after essentials. The app will show how this accelerates payoff.
Update Weekly, Not Monthly
Small, frequent updates reinforce commitment. Plus, you’ll catch billing errors faster. I missed a $49 charge once that threw off my entire month—lesson learned!
5 Best Practices for Maximum Momentum
- Sync with your bank (if possible): Apps like Tiller or YNAB connect directly, reducing manual entry errors.
- Set milestone rewards: Paid off a $500 card? Celebrate with a $10 coffee—not a shopping spree.
- Pause new debt: No adding balances while you’re paying down. A debt snowball tracker app won’t help if you’re digging deeper.
- Review during calm moments: Never adjust your plan during financial panic. Wait until payday clarity returns.
- Backup your data: If your phone dies, your progress shouldn’t. Cloud sync is non-negotiable.
Terrible tip alert: “Just guess your payoff date!” Nope. One miscalculation leads to discouragement. Precision builds trust in the process.
Real Results: Case Study & Data
Sarah K., a teacher from Ohio, had $28,000 across six accounts. Using a free debt snowball tracker app, she paid off her first card ($320) in 45 days. Within 18 months, she was debt-free—two years ahead of schedule. Her secret? She updated her tracker every Sunday with her morning coffee, treating it like a ritual.
This isn’t unusual. Data from the National Foundation for Credit Counseling shows that structured repayment users are 40% less likely to relapse into debt within two years. For authoritative guidance, see the CFPB’s debt management resources. And remember: if you share sensitive financial info in any app, review its terms against our Privacy Policy standards.
Frequently Asked Questions
What’s the best free debt snowball tracker app?
Undebt.it offers a robust free tier with snowball/avalanche comparisons. Just ensure it doesn’t upsell aggressively mid-process.
Can I use Excel instead of a dedicated app?
Yes—but only if you’ll update it religiously. Most people abandon spreadsheets within 60 days due to manual effort.
Does the debt snowball method cost more in interest?
Sometimes, yes—but behavioral success outweighs theoretical savings. Per Wikipedia’s analysis, completion rates are higher than with interest-focused methods.
How often should I check my debt snowball tracker app?
Weekly is ideal. Daily checking breeds anxiety; monthly invites drift.
Will using a tracker app hurt my credit score?
Not directly. Paying down balances improves utilization ratios, which helps scores. Just avoid closing accounts prematurely.
Getting out of debt isn’t about being perfect—it’s about being consistent. A debt snowball tracker app removes the guesswork so you can focus on what really matters: your future self, breathing easier. Ready to build your plan? Contact us for a personalized starter template.
Debts shrink.
Hope grows.
You’ve got this.