If you’ve ever stared at a mountain of credit card statements and felt utterly paralyzed, you’re not alone. I once paid the minimum on five cards for two years—watching interest balloon while my motivation flatlined. Then I discovered the debt snowball method… and promptly botched it by skipping a critical step: consistent tracking. Without a reliable snowball debt tracker, even the best plan crumbles. In this guide, we’ll fix that.
Table of Contents
- Why Tracking Matters More Than You Think
- Your Step-by-Step Snowball Plan
- Snowball Success: Best Practices That Stick
- Real People, Real Results
- Frequently Asked Questions
Key Takeaways
- A snowball debt tracker turns abstract goals into visible progress.
- The debt snowball method prioritizes smallest balances first—psychological wins drive momentum.
- Free tools and simple spreadsheets often outperform expensive apps.
Why Tracking Matters More Than You Think
The debt snowball method, popularized by Dave Ramsey, works because it leverages human psychology: quick wins build confidence. But without accurate, up-to-date tracking, those wins vanish into spreadsheet limbo. According to a 2023 Federal Reserve report, nearly 45% of U.S. adults carry credit card debt—and over half feel “anxious” about repayment. A snowball debt tracker cuts through that anxiety by making every dollar count.
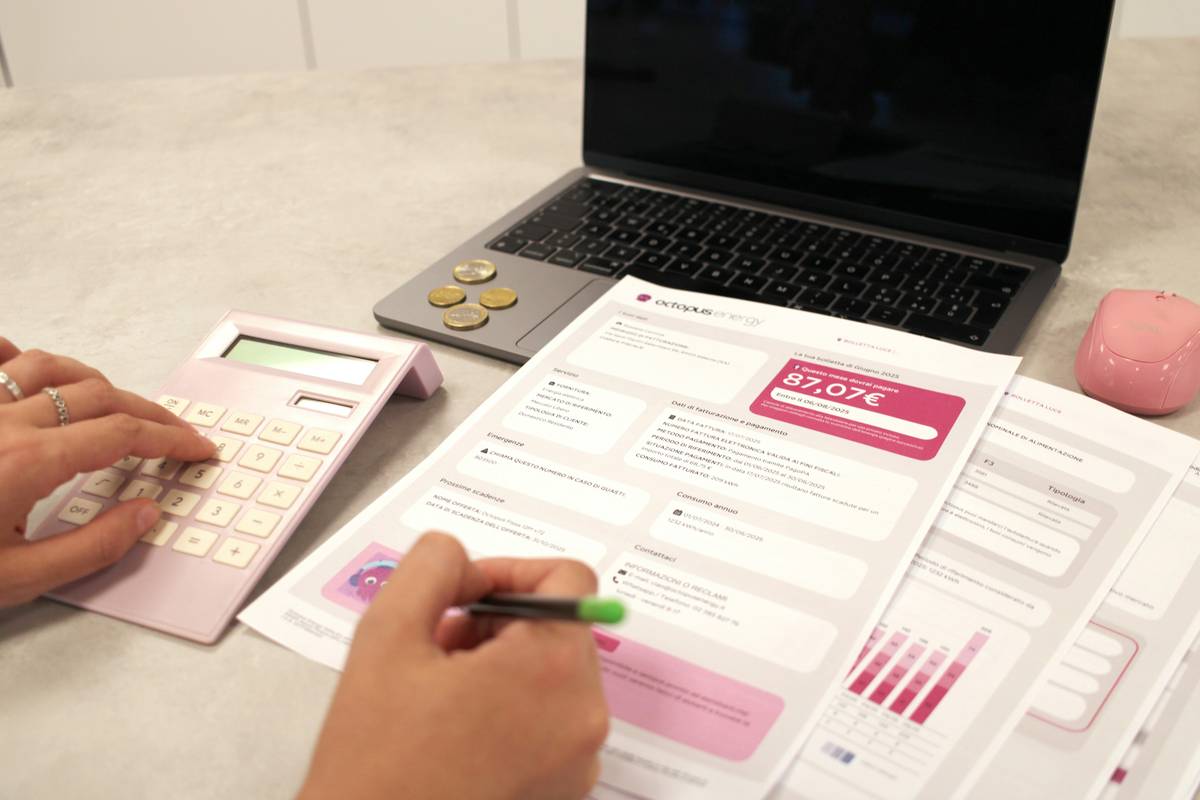
I made the classic error: listing debts once, then never updating balances after payments. Two months in, I lost track of which card I’d just paid off—and accidentally duplicated a $100 payment. That’s $100 I couldn’t redirect to the next debt, stalling my snowball mid-roll. Don’t be like me.
Your Step-by-Step Snowball Plan
List Every Debt (Smallest to Largest)
Ignore interest rates for now. Order debts by balance—from $50 medical bill to $8,000 car loan. This list is your battlefield map.
Set Minimum Payments
Keep paying minimums on all debts except the smallest. Redirect every spare dollar to that one balance. Once it’s gone, celebrate—then roll that payment amount into the next debt.
Log Every Payment Immediately
This is where your snowball debt tracker becomes non-negotiable. Use a notebook, Excel sheet, or free app—but update it the same day you pay. Delayed logging breeds confusion.
Snowball Success: Best Practices That Stick
- Automate what you can: Set calendar alerts for due dates and weekly tracker updates.
- Visualize progress: Shade in a debt thermometer each time you hit 25% payoff milestones.
- Avoid the “terrible tip” trap: Never skip an emergency fund to accelerate debt payoff. One flat tire shouldn’t derail your entire plan. Build a $500 buffer first.
- Pet peeve rant: Why do finance “gurus” shame people for using the snowball over avalanche (interest-first) method? Math matters, but consistency matters more. If avalanche demotivates you, you’ll quit. Period.
Real People, Real Results
Sarah K., a teacher from Ohio, paid off $22,000 in 18 months using a handmade snowball debt tracker. She started with a $300 dental bill, then rolled payments upward. Her key insight? “Crossing off that first debt gave me chills—it proved I could actually win.” Her tracker included columns for balance, payment date, and emotional rating (1–5 stars). Those tiny wins built unstoppable momentum.
Data supports this: A 2021 study in the Journal of Consumer Research found that consumers who focused on small, achievable goals were 32% more likely to eliminate debt than those fixated solely on total amounts. (Source)
Frequently Asked Questions
What’s the difference between a snowball debt tracker and a regular budget app?
A dedicated snowball debt tracker focuses exclusively on debt balances, payoff order, and payment rollovers—not general spending. It’s leaner, faster to update, and psychologically tuned for debt elimination.
Can I use a spreadsheet instead of an app?
Absolutely. Google Sheets or Excel works perfectly. Just ensure it includes columns for creditor, balance, minimum payment, snowball payment, and payoff date.
How often should I update my tracker?
Immediately after every payment. Delaying creates guesswork—and guesswork kills momentum.
Does the snowball method work for student loans?
Yes, but group federal loans separately if they share a servicer. Treat each unique balance as its own “debt” in your tracker.
Where can I learn more about Jiva’s approach to debt freedom?
Our team at Jiva Management combines behavioral science with practical finance—because lasting change starts in the mind. We’ve walked this path ourselves.
Is my data safe if I build my own tracker?
If you’re storing sensitive account numbers, review our Privacy Policy for best practices on protecting personal financial info.
Debt freedom isn’t about perfection—it’s about showing up, tracking truthfully, and celebrating tiny victories. Ready to build your custom plan? Contact us for a free 15-minute strategy session. Because everyone deserves to sleep soundly—without creditor dreams.
One step, then another. The snowball grows.